Mortgage guidance without the pressure.

The perfect time to buy doesn't exist.

Let's get you into a home where you're safe and secure, with a payment you're comfortable with—because life happens.

Why I do this

A home is more than a house.

A warm front porch with a Ryno's Porch mug and journal

Buying a home can feel intimidating. I remember worrying about the job, the credit score, the money—and wondering what would happen if something went wrong.

Then I became a homeowner. I learned how to fix a sprinkler. I built things. I changed things. I watched the dogs run around a fenced backyard and realized I could make that place ours.

That is what changed for me: the little problems became part of the pride. The house wasn't just somewhere I lived. It was a place I could shape, protect, and fill with memories.

That's how I think about my job. The mortgage matters, but the home is the reason. I want to help you find a payment you can comfortably live with—because life happens.

From the front porch

Front Porch Notes

Little stories and observations about homeownership—and why the place we call home matters.

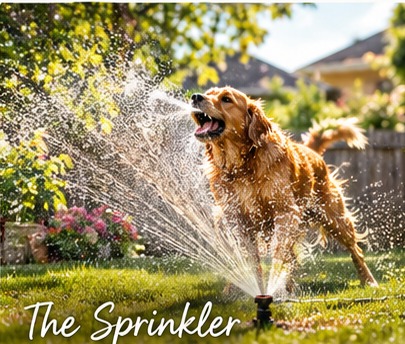
A backyard sprinkler watering the lawn on a sunny day

Front Porch Note No. 1

The Sprinkler

My first real lesson in homeownership wasn't about interest rates or equity. It was a sprinkler that needed fixing.

Read the note

I remember digging around a sprinkler and thinking, “Now what?” There wasn't a landlord to call. There wasn't somebody else who owned the problem.

So I went to Home Depot, figured it out, and fixed it.

It sounds small. But it mattered. I wasn't just living in somebody else's house anymore. I was taking care of my home.

That's one of the funny things about owning a home. Responsibility and pride show up together. Sometimes they're the same thing.

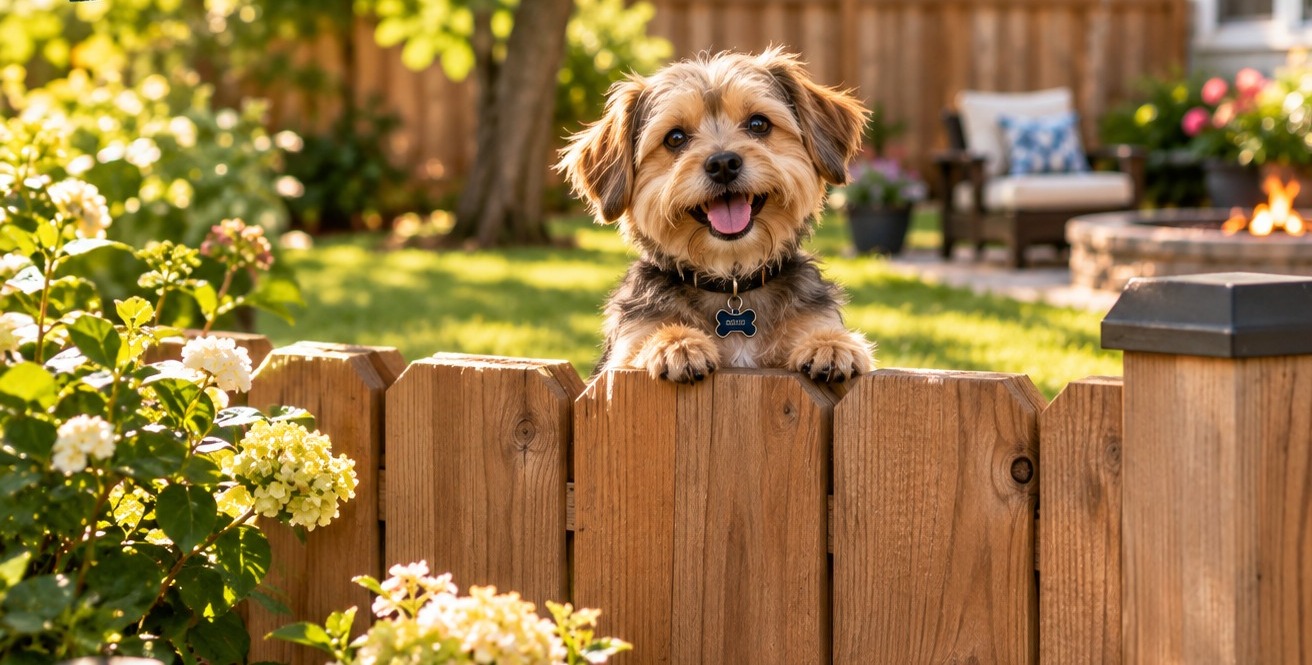
A small happy dog safely enjoying a fenced backyard

Front Porch Note No. 2

The Fence

Sometimes a fence is more than a fence. Sometimes it's the feeling that everyone—and every dog—has a safe little place to belong.

Read the note

I loved watching the dogs run around the backyard. And there was something satisfying about knowing the fence was ours.

We could change it when we needed to. We could make the yard work better for our family. And when the dogs were outside, I could relax knowing they had room to run without having a chance to wander off.

It sounds like a small thing. But that's the kind of small thing that makes a house feel like your home.

Owning a place isn't just about the big decisions. Sometimes it's the freedom to make the little ones.

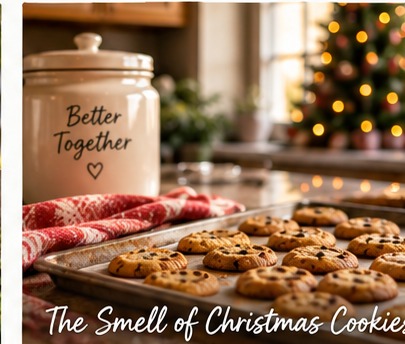
Freshly baked Christmas cookies in a warm home kitchen

Front Porch Note No. 3

The Smell of Christmas Cookies

Kids don't remember the square footage. They remember what home felt like.

Read the note

Years from now, I don't think children will remember how many closets a house had.

They'll remember the smell of cookies at Christmas. The backyard. The tree they climbed. The friends down the street. The ordinary Tuesday nights that somehow became the good old days.

That's the magic of a home. It gives life a place to happen.

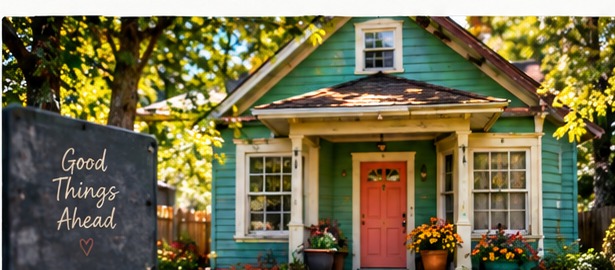
A colorful older home with a welcoming front porch

Front Porch Note No. 4

The House That Said Come On In

After nearly thirty houses, the one we chose wasn't the prettiest. Somehow, it felt like the one that wanted us there.

Read the note

My dad was our real estate agent, and he walked us through close to thirty homes. By the time we got to this one, my wife was burned out from looking.

And I'll be honest—the color of the house was one of the ugliest I'd ever seen. I had to talk her into going inside.

But once we did, something felt different. It was hard to explain. It almost felt like the house was saying, “Come on in. I want you here.” Like it was ready to keep us safe, give us room to make it ours, and let us change things a little at a time.

We didn't need to look at another house. FINALLY!

We went back, made an offer, and thirty days later we had the keys. We started making it ours little by little.

Sometimes you don't choose a house because it's perfect. Sometimes you walk through the door and realize it feels right.

A comfortable front porch glowing at sunset in a neighborhood

Front Porch Note No. 5

This Is Home

It wasn't finished when we bought it. Ten years later, it isn't finished now. That's part of what makes it ours.

Read the note

When we first bought our house, nothing was updated. The floors, paint, doors, windows—pretty much everything needed some attention. At first, it felt a little overwhelming.

But over the years, we changed things little by little. Flooring. Paint. Doors. Windows. The patio and awning. Sheds, a barbecue, grass, the yard, and comfortable places to sit. We added a fire pit and made the front porch a place we actually wanted to spend time.

The fence has had its own history. We extended it, pulled it back, and extended it again when we needed room for our grandson's trampoline.

We've changed cupboards and the sink, updated bathrooms, lights and fans, and even pulled up carpet to bring the original hardwood back to life.

And sometimes, when the porch lights are on and we're sitting outside watching the neighborhood, an ice cream truck rolls by and kids still come running out for ice cream. The old trees have grown. We've planted newer ones. Life has happened here.

This house has become a place where my wife, my grandson, and our pets have a place they call home. We don't have to wonder where we'll make our next home. We have one.

We made it ours. And after all these years, the simplest way I can say it is this: This is home.
For home buyers

You don't have to have it all figured out.

Maybe you're ready to buy. Maybe you're six months away. Maybe you're just curious what a comfortable monthly payment might look like.

That's a conversation worth having before you start falling in love with houses. We'll look at your situation, talk through a payment that makes sense for your life, and build a plan from there.

Start a conversation →

Homebuying resources

Good information is worth having.

Here are a few resources I trust because the goal is simple: help you understand the process and make decisions that fit your life.

Why the CFPB? The Consumer Financial Protection Bureau is the federal agency focused on protecting consumers in financial products like mortgages and credit. Translation: it’s a useful place to get the facts without somebody trying to sell you something.

CFPB

How mortgage payments are calculated

Understand principal and interest—and why the total payment can be higher once taxes and insurance are included.

Read the CFPB article →

CFPB

What makes up a mortgage payment?

A straightforward explanation of principal, interest, mortgage insurance, taxes, and homeowners insurance.

Read the CFPB article →

CFPB

How much home can you comfortably afford?

A useful reminder that what you qualify for and what fits comfortably in your monthly budget are not always the same thing.

Read the CFPB article →

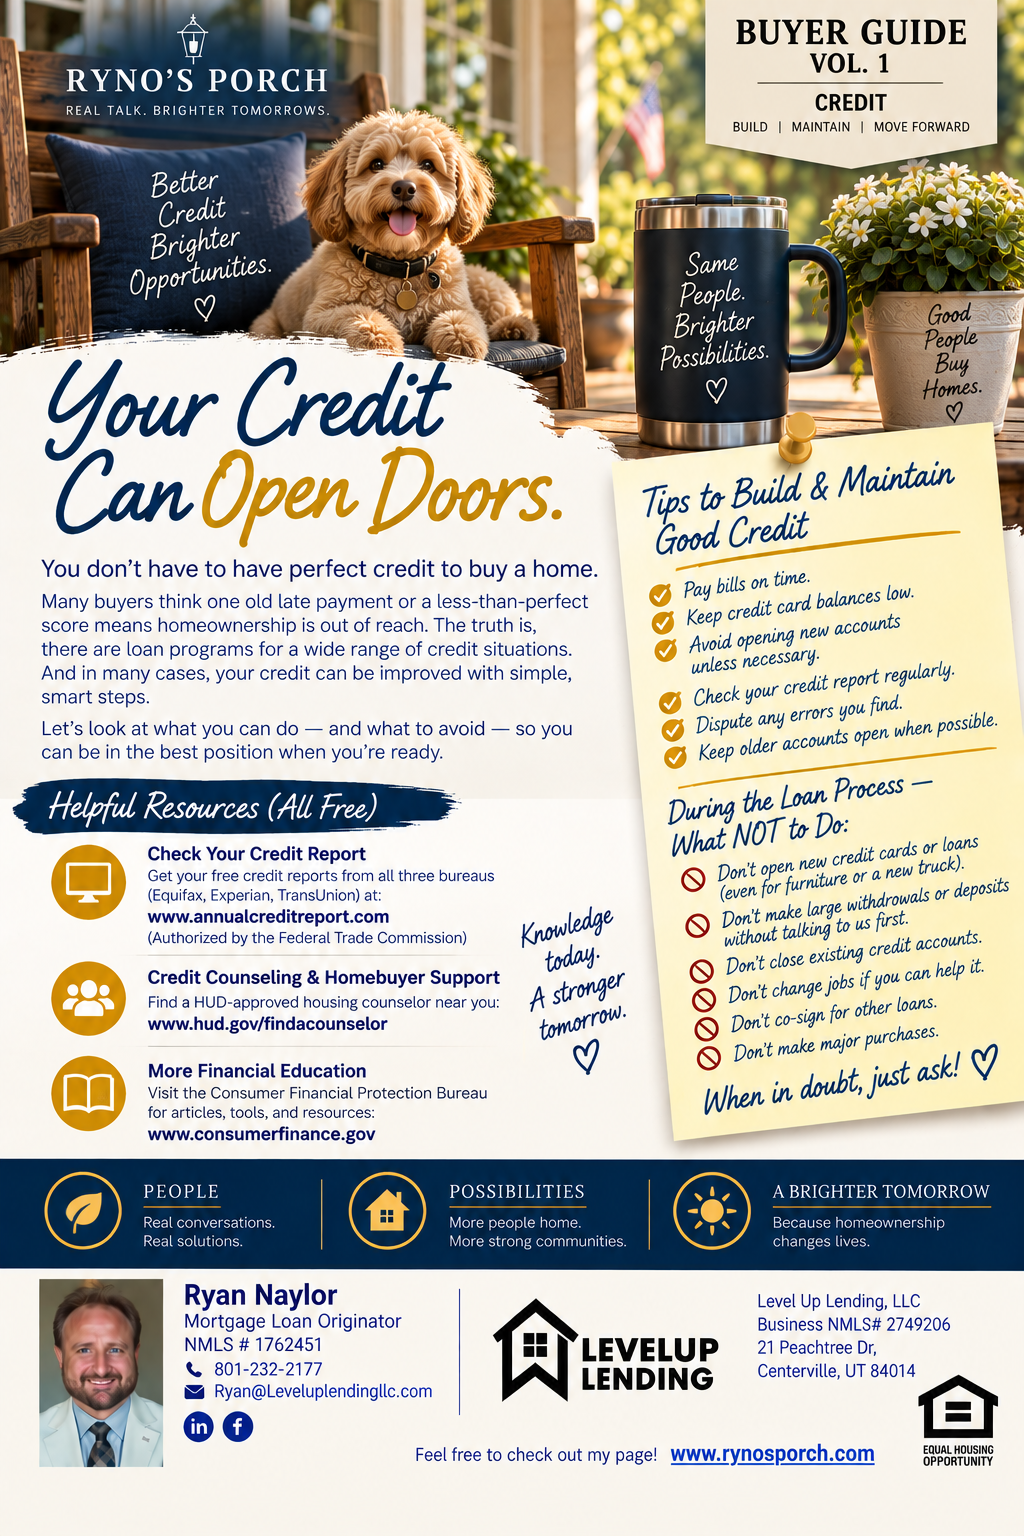
Check your credit

Start with the official source.

AnnualCreditReport.com is the ONLY authorized online source under federal law for free credit reports from Equifax, Experian, and TransUnion.

Be careful with websites that advertise “free” reports but may try to sell credit monitoring, trials, or other products.

Learn about free credit scores from the CFPB →

Buyer Guides

Useful now. Easy to come back to later.

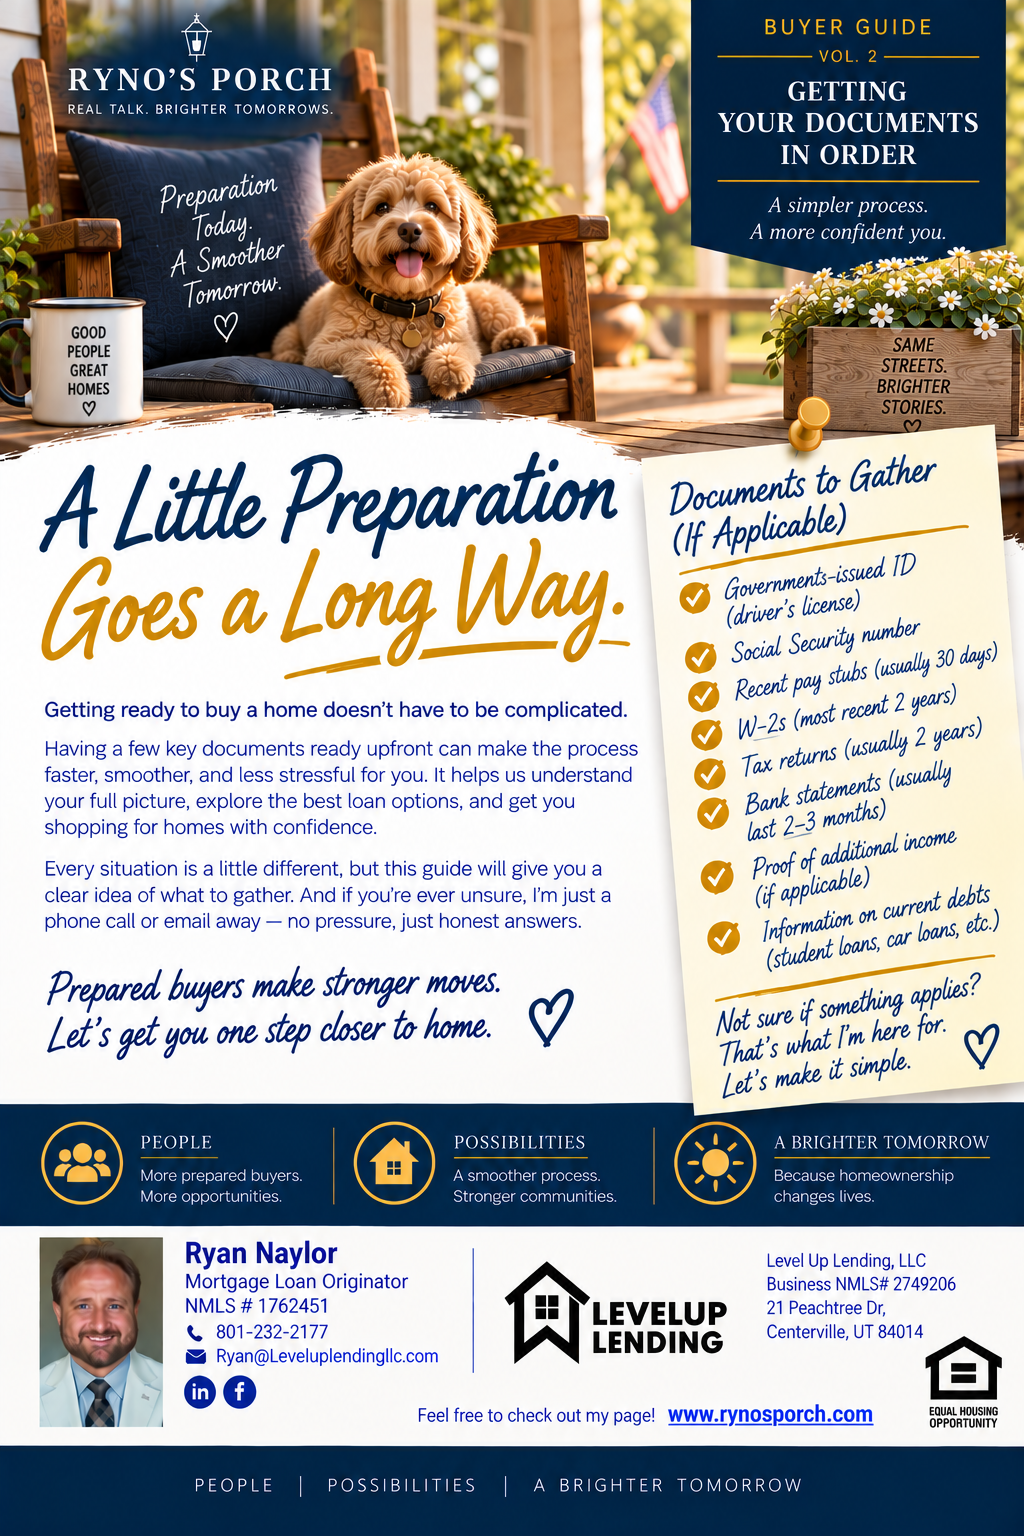
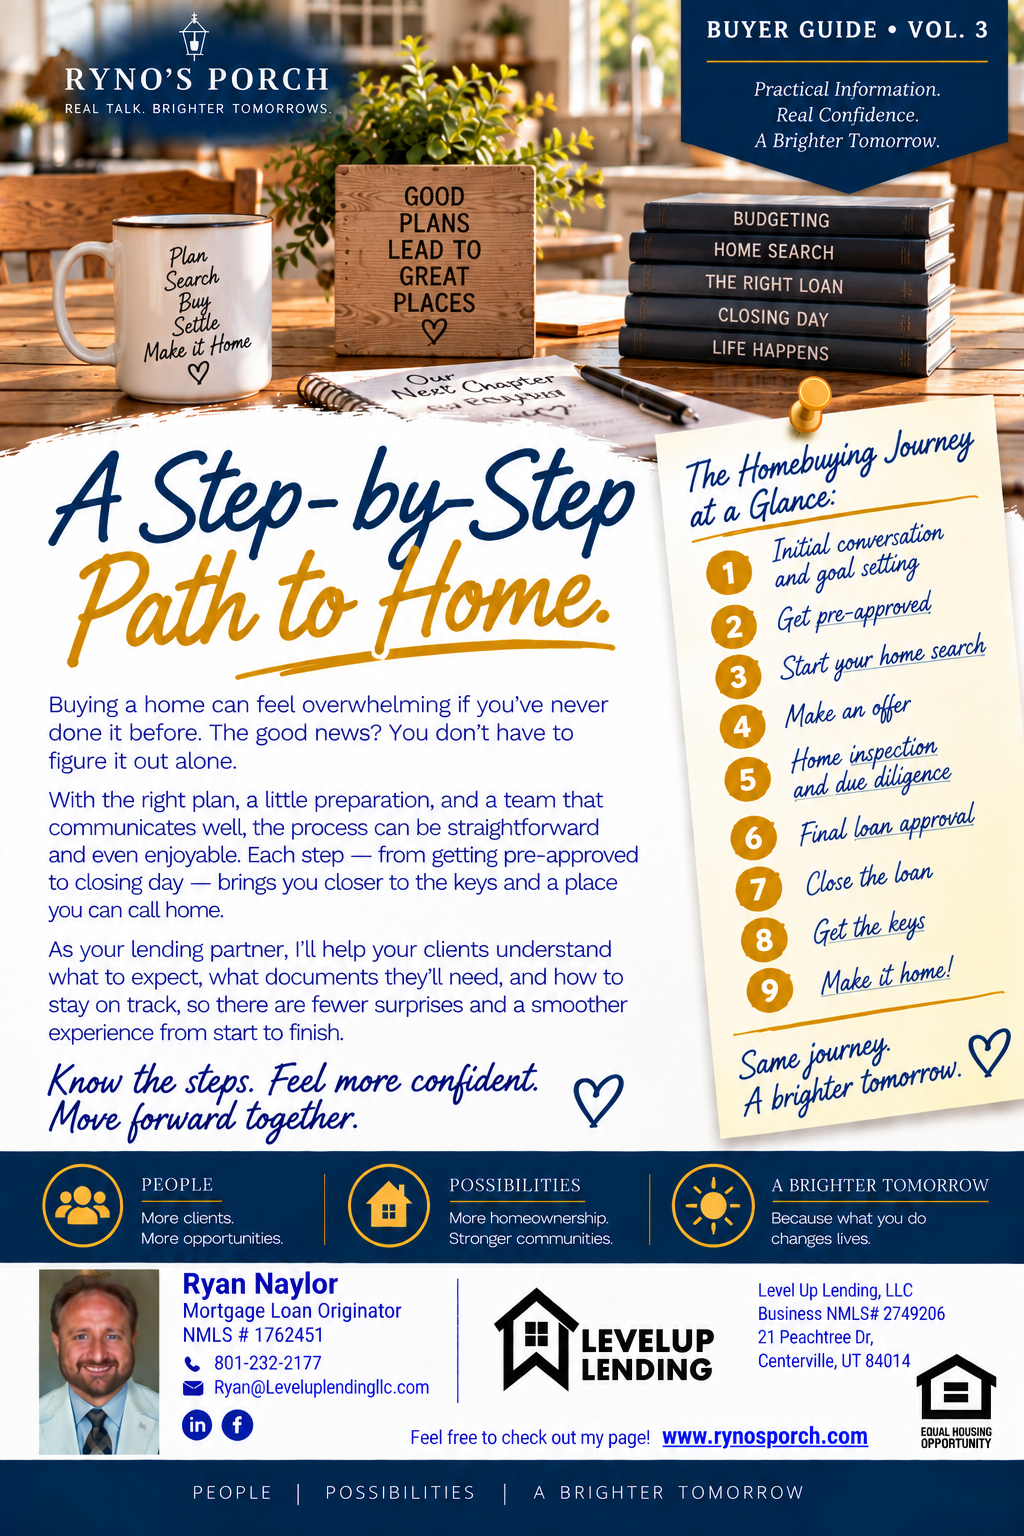
Practical, save-worthy information for different parts of the homebuying journey. No homework assignment and no required order—just open the one that helps today.

Credit shelf

Want to understand your credit a little better?

These are resources, not a step-by-step program. Some ideas overlap on purpose—open what looks useful and skip what doesn’t.

Credit resource

Your Credit & Your Next Home

A practical overview of what matters, what to check, and what to be careful about while you’re getting ready.

Open the resource →

Credit resource

Understanding Your Credit Score

Credit report versus credit score, common factors that affect a score, and why you don’t need to chase a magic number.

Open the resource →

Deeper dive

Ryno’s Credit Roadmap

A longer resource for buyers who want more detail on reviewing reports, errors, disputes, habits and getting mortgage-ready.

Open the roadmap →

Useful while you’re shopping

Take something with you.

A couple of practical tools for the part where the houses—and eventually the kitchens—start running together.

Printable

Ryno’s Porch House-Hunting Sheet

One house at a time, then a three-house short list. Keep track of what actually mattered—not just the countertops.

Open the house-hunting sheet →

After you get the keys

Home Maintenance Checklist

Simple checks for the home you worked so hard to make yours. Useful, unglamorous, and worth knowing where to find.

Open the checklist →

Real Mortgage Situations

Real scenarios. Real solutions. Because life happens.

Mortgages don’t always follow the perfect little path on the brochure. Something changes, a report comes back differently than expected, or a problem shows up halfway through. That doesn’t always mean the answer is no.

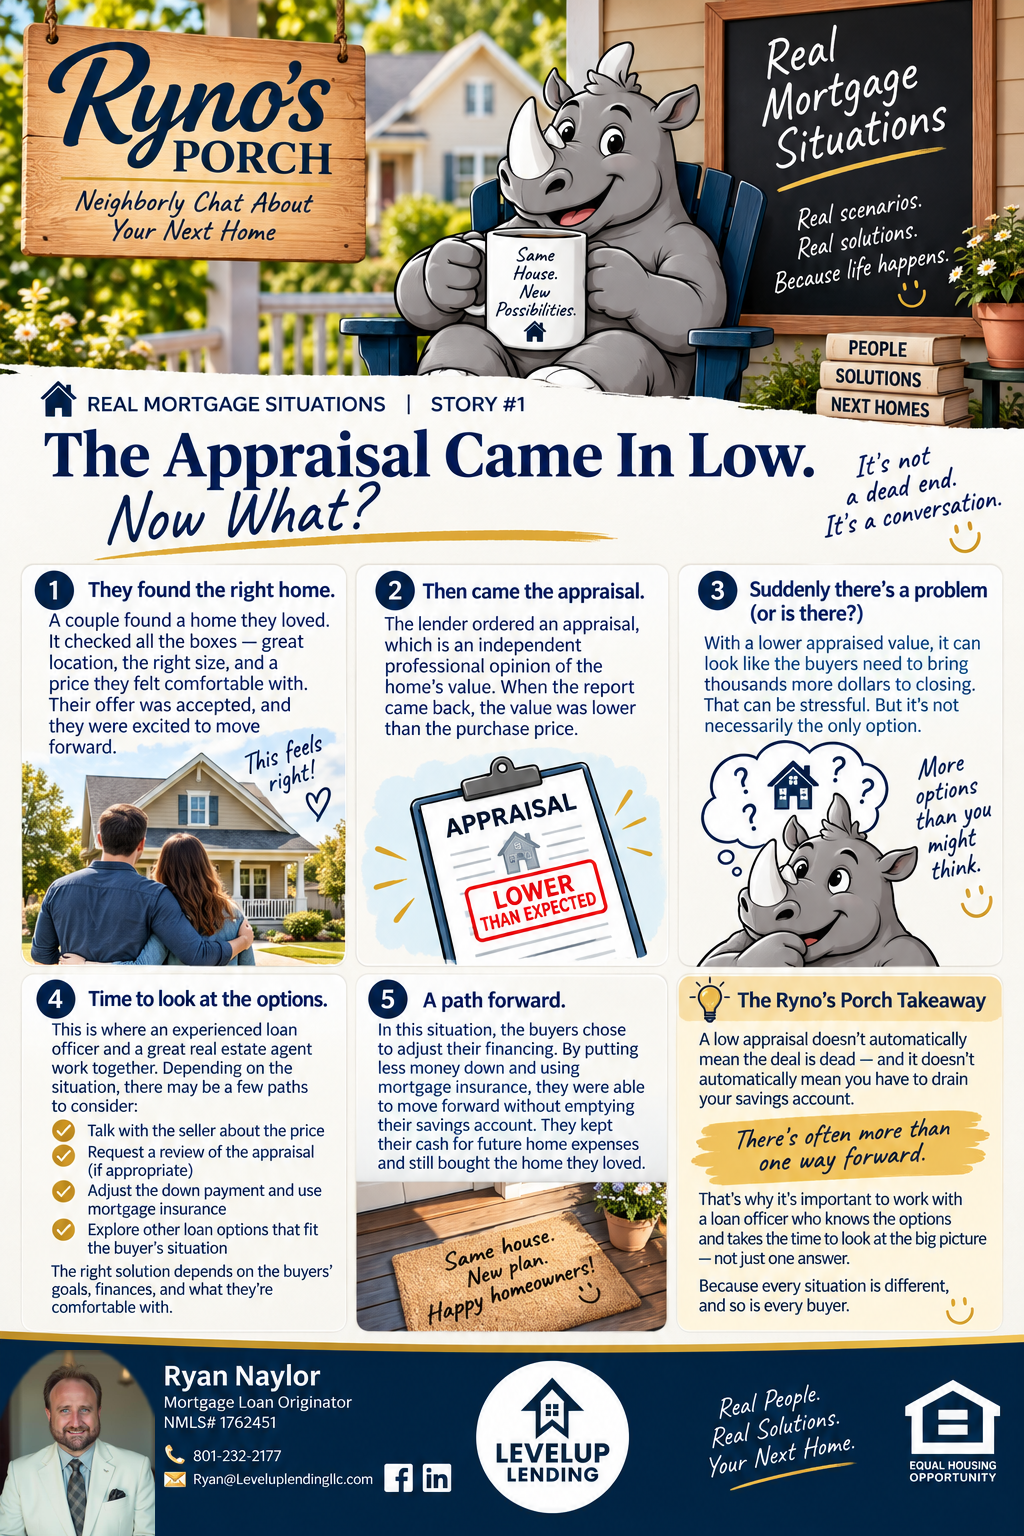
Real Mortgage Situations Story 1: The Appraisal Came In Low. Now What?

Story #1

The Appraisal Came In Low. Now What?

A lower appraisal can make it look like the buyer suddenly has to bring thousands more to closing. Sometimes there are other paths worth exploring. This story shows one real-world way to think through it.

Educational scenario only. Every buyer, property and loan is different.

Read Story #1 →
Ryno’s PorchREAL CONVERSATIONS. BRIGHTER TOMORROWS.
Take a seat.
Run some numbers.
See what’s possible. ♡
⚠ WARNING: HOUSE SHOPPING MAY OCCUR Side effects may include open houses, saved listings, unauthorized neighborhood drive-bys, arguments about countertops, spontaneous conversations about fenced backyards, and sudden opinions about kitchens. If symptoms persist, contact your Real Estate Agent. 😂
Wait a minute…What if it really is possible?

MORTGAGE PAYMENT CALCULATOR

Let’s Run the Numbers

Okay… what if it was THIS house? Put in the price and play with the numbers. No application. No phone number. No email. No sales pitch.

%
30 years
Estimated Monthly Payment—PRINCIPAL & INTEREST · 30-YEAR FIXED

Just a starting point. A full housing payment can also include property taxes, homeowners insurance, mortgage insurance when applicable, and HOA dues.

Numbers don’t tell the whole story,
but they’re a good place to start. ♡
NOW LET’S CONNECT THE DOTSTHESE NUMBERS ARE PART OF THE SAME CONVERSATION.

So… should I keep renting and save more, or buy sooner?

That’s usually the question hiding underneath all these numbers. Saving longer may mean a larger down payment—but it can also mean more months of rent along the way.

Let’s see what your numbers look like. Start with your savings timeline, then watch what happens to the rent paid during that time. After that, try changing where some of your monthly money goes and see how that could change the timeline.

1 · SAVE→2 · SEE THE RENT→3 · TRY A DIFFERENT MONTHLY PLAN

Show My Timeline

What if we wanted to put a little more down?

Save a little money before we jump in? Or, if you already have a down payment in mind, how long would it take to get there?

More to save—
Time to that goal—
P&I with that down payment—

Try $750. Try $1,000. Suddenly a big number becomes something you can envision.

Next → follow the timeline

Now that you can see how long saving might take, there’s another number worth seeing: how much rent happens during those same months?

While we’re curious…

How much rent happens while we’re saving?

Use your actual rent—or your best guess. The savings timeline below shows how long you may be saving. This shows how much rent could happen during those same months.

Over —, that’s about—in rent during that same savings timeline
Next → try changing the timeline

Seeing that rent number might raise another question: could money already going out each month eventually become extra down-payment savings? Let’s play with that next.

One more question

What if I changed where some of my money goes?

Could paying down a monthly obligation free up more money to put toward the down payment? No budgeting lecture. Just a quick look at how much is going out—and where—and what changing that could do to your savings timeline.

Already going out every month$0
What if some of that became savings?$0

Maybe one of these payments ends or gets paid down. If that money became down-payment savings instead, what could it do to the timeline?

Nothing changes unless you choose to try it.
Better
Conversations
Brighter
Tomorrows
♡

Honey… come look at this.

Most mortgage calculators give you an answer. This one might start a conversation.

Maybe the conversation isn’t whether you’d like to own a home anymore. Maybe it’s when—and how you’d like to get there.

When you’re ready to find out what your actual options look like, that’s where Ryno comes in.

For Real Estate Agents

Give your buyers something worth sharing.

Your clients don’t need another sales pitch. They need useful information, simple explanations, and people who can help when the transaction doesn’t go exactly according to plan.

Grab a Buyer Guide. Share a Real Mortgage Situation. Send them a calculator they can actually use without giving anybody their phone number.

A note from Ryno

Your clients see the house. They don’t see everything you do.

The showings, late-night questions, second guesses, negotiations, paperwork and emotional moments matter. A great agent does more than open doors—you help people find a place to call home.

Open the agent note →

Start here

Hey, I’m Ryno.

A quick introduction to how I work with agents and buyers: direct access, more options, problem-solving, and staying involved through closing.

Open the introduction →

Share with buyers

Buyer Guides

Practical pieces your buyers can save, read and come back to without being pushed into a lead form.

Browse Buyer Guides →

Share with buyers

House-Hunting Sheet

A printable tool buyers can take to showings—and a short-list page for when every kitchen starts becoming “the one with the island.”

Open the printable →

When life happens

Real Mortgage Situations

Real-world mortgage problems explained without turning your client into a loan officer.

See the first story →

No lead form

The “Wait a Minute…” Calculator

Let your buyers play with a home price, down payment, savings timeline and their own monthly numbers—without handing over their contact information.

Try the calculator →

Something for you, too

Pull something off Ryno’s Bookshelf.

Practical ideas, worksheets and tools for the situations that come up in this business. No course. No sales funnel. No homework.

Visit Ryno’s Bookshelf →

Use what helps. Send your buyers here. I’ll take good care of them.

Ready for numbers?

Want a quick rate quote?

If you're ready to talk about today's options, send me an email. We'll start with a conversation about your situation and what you're trying to accomplish.

Email Ryan →

Let's talk

Have a question? Let's start there.

No pressure. No need to have all the answers. Just a conversation about where you are and where you'd like to go.